
Mortgage & HELOC
Mortgage and HELOC document fraud detection
Flag edited and AI-generated bank statements, pay stubs and IDs before you fund.
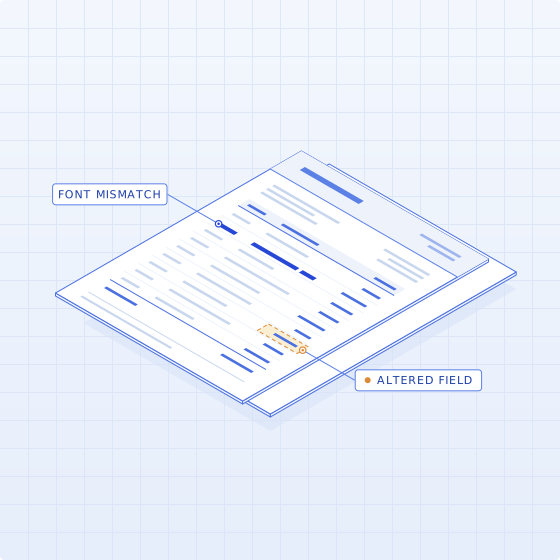
What we check
Key documents in the loan file. Checked before you fund.
01
Bank statements
Edited balances, deposits and fonts.
02
Pay stubs
Changed income, dates and employers.
03
W-2s & tax returns
Edited wages and figures.
04
IDs
Edited photos and details.
05
Property photos
Edited or AI-generated photos of the home.
06
Cross-document checks
Income compared across pay stubs, W-2s and deposits.
In developmentHELOC
HELOC document fraud detection
HELOC files often get lighter checks than a full mortgage. Trustable runs the same checks on each HELOC file.
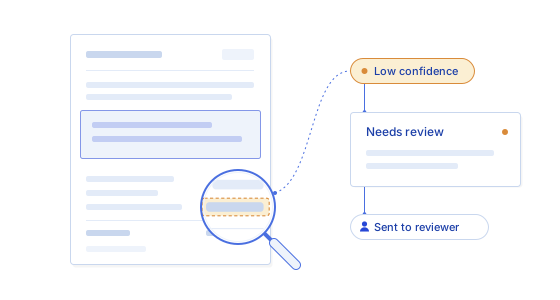
See why a file was flagged.
Your underwriter or fraud team decides.
01
Add the file
Bank statements, pay stubs, tax returns and IDs.
02
Check every page
Edits, AI generation and metadata.
03
Review the evidence
Each finding, where it is, how strong.
FAQ
Mortgage document fraud, answered.
What is mortgage document fraud?
Mortgage document fraud is the use of edited or fabricated documents to qualify for a loan: altered bank statements, pay stubs, W-2s, tax returns, appraisals or IDs. Income is the most common target. In Fannie Mae data for 2024, income accounted for 46% of misrepresentation findings, as reported by National Mortgage News. Generative AI makes convincing fakes faster to produce, which is why more lenders check the documents themselves, not just the numbers typed into the application.
Can Trustable detect fake bank statements?
Yes. Trustable checks each bank statement for edited text, font and layout mismatches, metadata that conflicts with the claimed source, and balances or totals that don’t add up across pages. Every finding is marked on the page with its strength, so an underwriter can see what looked wrong and decide whether to request the original statement or verify with the bank.
How are fake pay stubs detected?
Each pay stub is checked for signs of editing, such as changed figures, mismatched fonts or a rebuilt template, and each finding is marked with its strength. Comparing the stub’s income with the W-2s, tax returns and bank deposits in the same file is in development, so a stub that looks clean on its own but disagrees with the deposits can still be flagged.
Why do HELOC lenders need document checks?
HELOC applications often move faster and get lighter checks than a full purchase mortgage, so an altered income document or property photo has a better chance of getting through. Trustable runs the same checks on each HELOC file, including bank statements, pay stubs, tax returns, IDs and property photos, and shows the reviewer the evidence for each finding.
How do files reach Trustable?
Through the API or the Trustable web app. Send a statement, pay stub, W-2 or ID and get back the findings, where they are and how strong each one is, for your underwriter or fraud team. Routing results into your workflow is in development.
Does a flag mean the borrower committed fraud?
No. A flag means a document needs a closer look, not that anyone committed fraud. Files are edited for innocent reasons too, such as cropping a scan or removing a password. Trustable shows what it found, where, and how strong the signal is; your underwriter decides whether to ask for the original or move on.
Mortgage & HELOC
Check your next loan file.
See it on a sample loan file. We agree on data handling before you share anything.
Book a demo